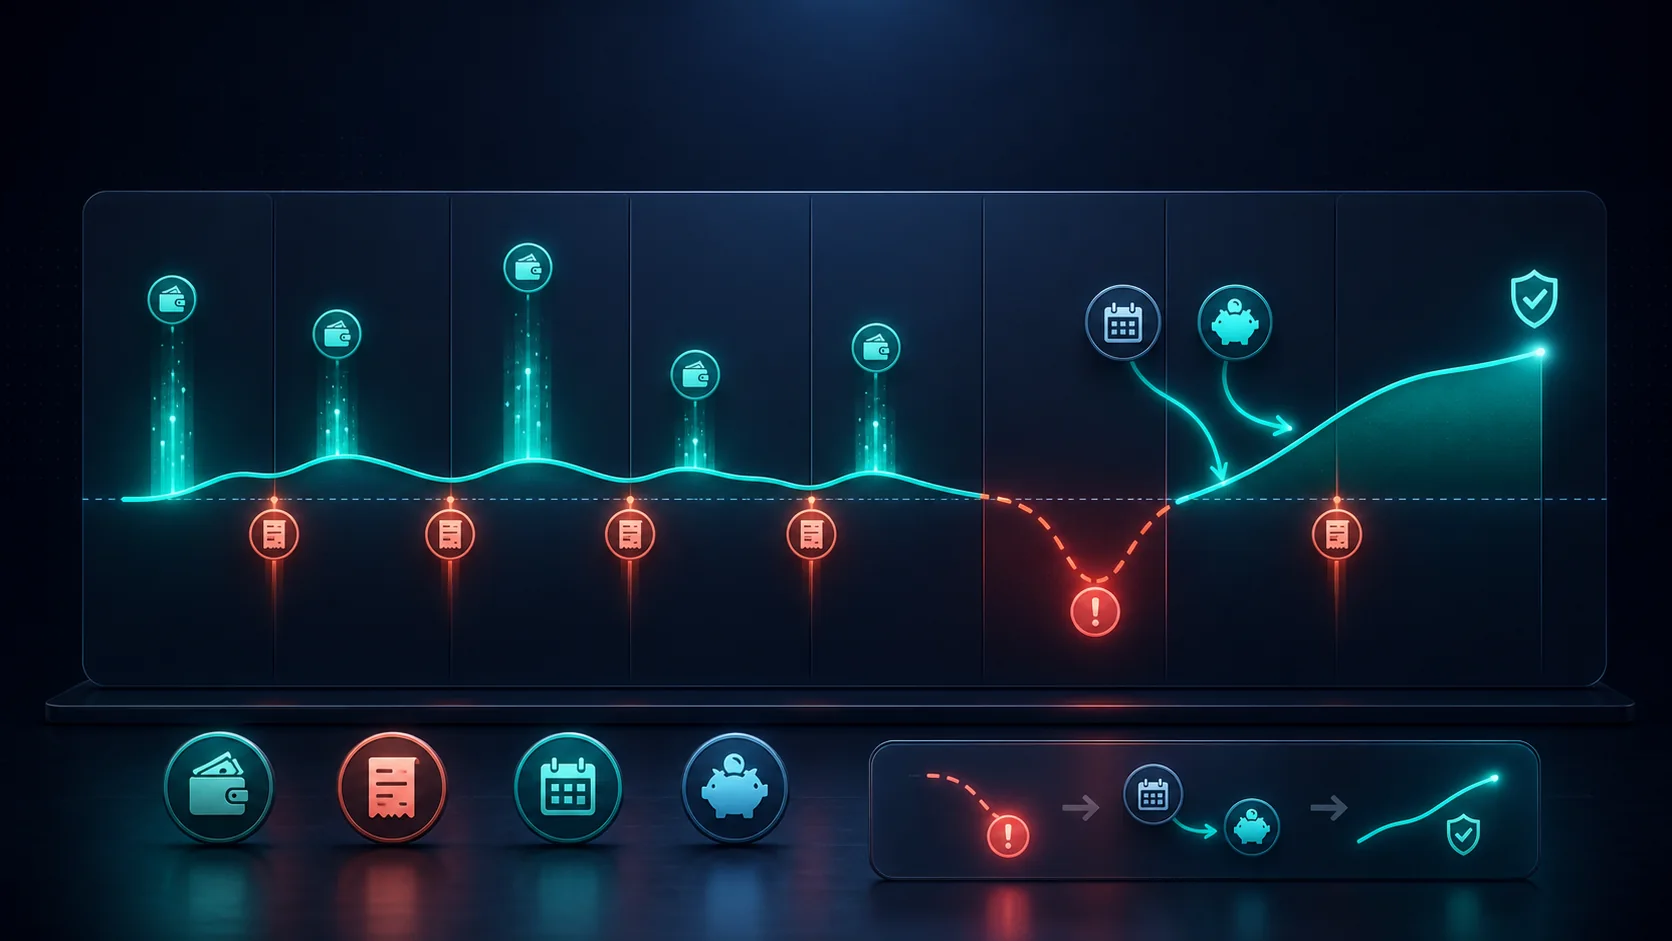
A monthly budget can look balanced while your account still runs short on the wrong Tuesday. A cash-flow budget solves a different problem: timing. In the CFPB’s own words, it “is all about tracking the timing of your income and expenses to make sure you have enough from week to week.”
Build the calendar from real transactions
Use at least the last 30 days. For every expected payment, record the date and a conservative amount. Then add rent, debt minimums, utilities, subscriptions, groceries, transport, and savings on their actual dates. Do not divide everything by four: a bill due on the third affects a different week from a bill due on the twenty-fifth.
Carry each weekly balance forward
For week one, write the opening balance, add income, subtract every expense, and calculate the ending balance. Copy that ending balance into the next week's opening balance. Repeat for eight weeks. A negative week is an early warning, even if the whole month is positive.
Fix timing before cutting everything
When a week goes negative, test changes in this order: move a flexible purchase, reserve part of a strong week's income, ask whether a creditor can change a due date, reduce a category temporarily, or add a small income action. Keep a minimum floor in the account so the plan includes ordinary uncertainty rather than assuming every estimate will be exact.
Your first eight-week plan
- Enter the current account balance as week one's opening balance.
- Add every expected income date using conservative amounts.
- Place bills and everyday spending in the week they actually occur.
- Carry each ending balance into the following week.
- Flag negative weeks and choose one timing fix for each.
Update the plan once a week. Lumy has no bank connection, so the actual amounts are the ones you record yourself: each week, compare them with your plan and update the estimates for the weeks ahead. In Lumy Pro, the cash-flow forecast also projects recurring payments and upcoming bills forward, so a tight week is visible before it arrives. The value comes from seeing a shortage while you still have choices.